Products · Lending
The full loan lifecycle, start to finish.
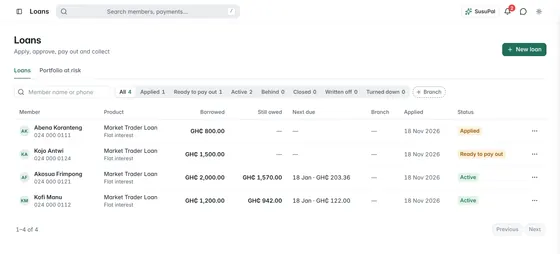
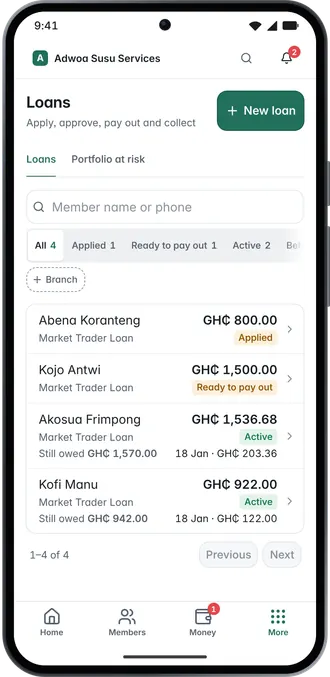
Application, approval, paying out, repayments, then settlement or write-off. Every step is recorded with who did it.
The opportunity
Arrears can sit unnoticed until someone happens to open the file, and portfolio risk is usually only visible once a month, after the fact.
SusuPaa flags arrears automatically every night and reports portfolio at risk the moment you open the dashboard.
Why organisations choose Lending
One product, every loan
Define loan products with their interest method, tenor and rules. Every loan inherits them.
Secured or not, on the record
Savings-secured with a lien on the passbook, unsecured, or backed by external collateral, such as land, a vehicle, equipment or a guarantor. Each is recorded.
PAR, live
Portfolio at risk by ageing bucket, available the moment you ask.
A second person, when you want one
Turn on two-person approval and approving, paying out and writing off a loan each need a second person.
Watch it work · 1 min 49 sec
A loan from application to repayment. Lend a member GH₵ 200.00, take repayments in cash and by phone, then settle early.
Read what the video says
A loan is a promise in both directions. Here's one, from the first application to the final repayment.
Start with the loan product. Set the interest, the fee, the term, and how much a member can borrow against their savings. The preview shows what a member will pay.
To apply, choose the member, the savings that back the loan, and the amount: GH₵ 200.00 over three months.
Submit it for approval. A second admin signs off, and the repayment schedule appears. Then pay it out, and record how the money moved.
When a repayment comes in as cash, record it. It clears the oldest instalment first.
Members can repay from their own phone. They open the loan, see what's due, and pay with mobile money.
To finish early, settle the loan. The payoff is worked out for today. The loan closes, and the held savings are released.
Every payment stays on the record. Loans on SusuPaa: clear from start to finish.
The lifecycle
From application to write-off, on the books. Nothing about a loan lives in a spreadsheet beside the system.
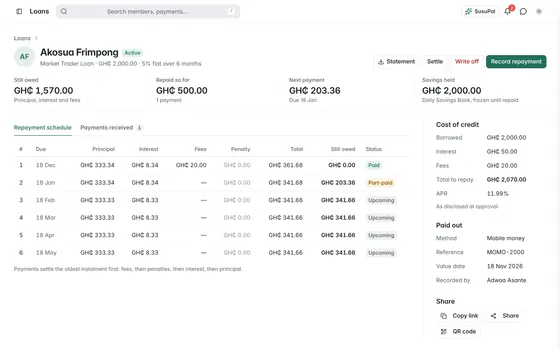
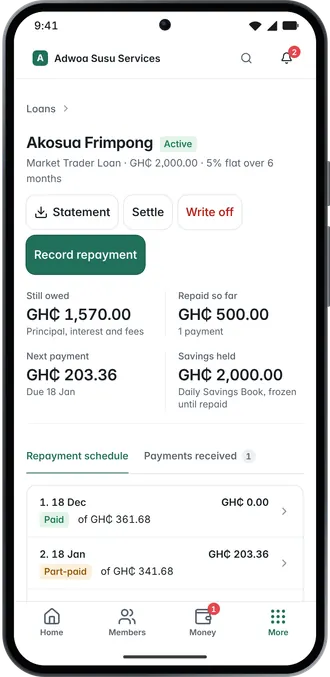
A loan starts as an application, from staff or from the member in the portal, against a defined product. Approval, disbursement and every repayment are separate acts with their own roles. The amortised schedule is generated at disbursement, and each repayment settles interest and principal by rule.
Flat or reducing balance
Choose per product. Weekly or monthly tenor and repayment.
Amortised schedule
Every instalment is a row with a due date, expected interest and expected principal.
Pre-agreement disclosure
Before a member accepts, they see the total cost of credit. It is part of the record.
Risk and provisioning
See arrears the day they start. PAR buckets and provisioning post straight to your books.
Arrears are flagged automatically as instalments fall due. Portfolio at risk is reported by ageing bucket whenever you open it. When you start a provisioning run, it posts loan-loss provisions to their own accounts, so your books show the risk you carry.
PAR by ageing bucket
Current, one to thirty days, thirty-one to sixty, sixty-one to ninety, ninety plus.
Provisioning runs
Start a run and SusuPaa sets money aside against each bucket by your rates. The entries post to your books.
Write-offs, controlled
A write-off is a permissioned act with its own journal, never a deletion.
5
ageing buckets, from current to ninety-plus days, reported on demand.
Collateral and control
What secures the loan is recorded with it.
Savings-secured loans place a lien on the passbook. External collateral, such as land, vehicles, equipment, inventory or a guarantor, is recorded against the loan. Disbursement and write-off can be put behind dual control, so no single person moves money out or makes it disappear.
Liens on passbooks
The secured balance is held while the loan is open.
Collateral register
Type, description and value, tracked from pledged through claimed to liquidated.
Dual control on disbursement
A second approver before money leaves.
See the controls ›
Everything in the box
Rates, risk and collateral, all configurable.
- 01Flat or reducing balance
- Weekly or monthly, per product.
- 02Collateral, tracked
- Liens, land, vehicles, or guarantors.
- 03PAR by ageing bucket
- Available the moment you ask.
- 04Provisioning runs
- Configurable rates, by age bucket.
- 05Automated arrears
- Flagged nightly, no file needed.
- 06Member self-application
- Apply and track from the portal.
Works with
Passbooks
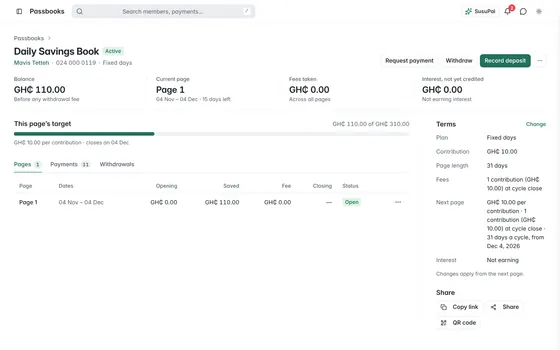
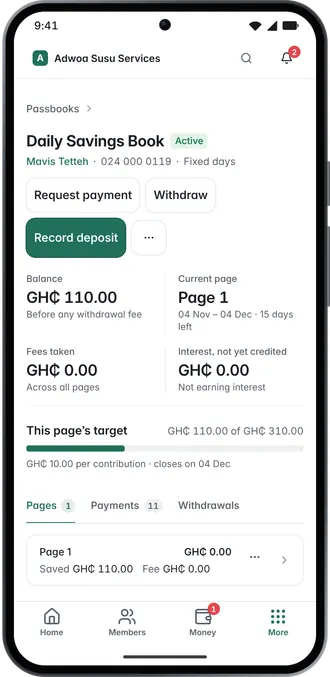
Pages, fees and a running balance, with an approval on every withdrawal. It is other people’s money.
Accounting
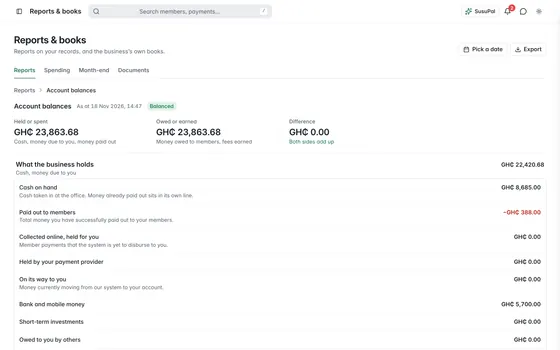
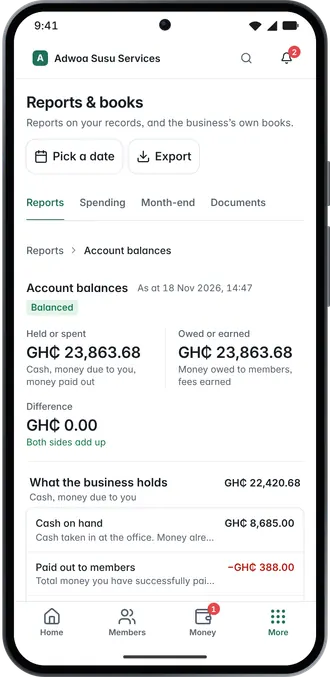
Books that always balance, on every plan. Each payment is recorded on both sides of the books, so your trial balance ties out and any accountant can check it.
Member portal
Members pay by mobile money, check their Ghana Card, apply for a loan, ask to withdraw and download statements, all from their own phone.
SusuPal
A read-only AI assistant for your SusuPaa account. Every answer comes from your own books, members, loans and reports. Never from memory, never invented.
FAQ
Questions people ask about lending
Can members apply for a loan themselves?
Yes, from the member portal, against a product you have made available. Staff still approve.
How is PAR calculated?
From the outstanding balance of loans with instalments overdue, grouped by how many days the oldest overdue instalment has been outstanding.
Can a member pay a loan off early?
Yes. The member sees what it costs to finish the loan today and can pay it from their phone. Staff can record an early settlement too.