Products · Passbooks
The classic passbook, modelled properly.
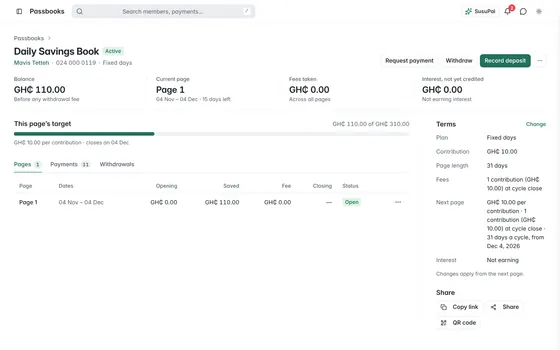
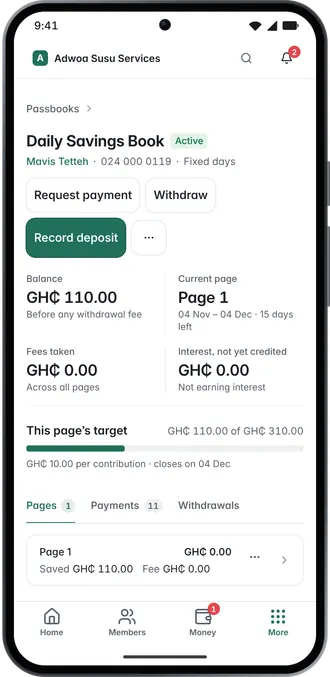
Pages, fees and a running balance, with an approval on every withdrawal. It is other people’s money.
The opportunity
A paper passbook can be lost, altered, or just left at home. A member and a collector can end up with two different ideas of the balance.
SusuPaa keeps one running balance that both sides can check, and a second approval before any withdrawal pays out.
Why organisations choose Passbooks
The book, modelled
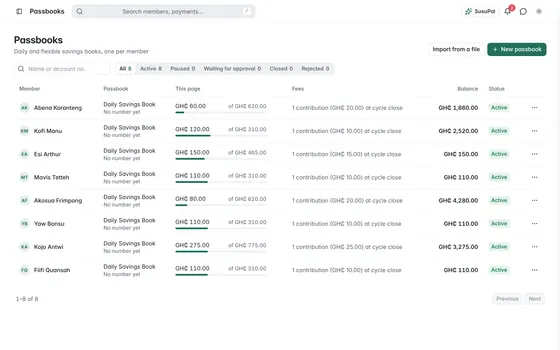
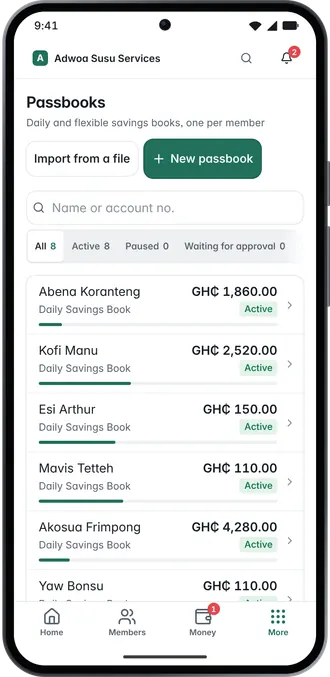
A running balance, cycles, pages and fees. The passbook your members know, with the risks of paper removed.
Fees, declared up front
Flat or percentage fees on deposit, at cycle close or on withdrawal, applied by rule and posted as their own line.
Interest, where the law allows it
If you are licensed to take deposits, interest is worked out every day and added once a month, as its own line.
Withdrawals need a second person
Because it is other people's money, every withdrawal is requested, then approved, then paid.
Watch it work
A passbook from first deposit to payout. Open a passbook, record deposits, let members save from their own phone, then pay out the page.
Cycles and fees
A passbook with a rulebook. Cycle length, fee mode and interest are properties of the product, decided once and applied every time.
Each passbook has a cycle: weekly, monthly, however your product works. Fees are configured once, as a flat amount or a percentage, charged on deposit, at cycle close or on withdrawal. When a cycle settles, the fee posts and the next cycle opens. Members see the same rules you do.
Cycle settlement
Open cycles close on schedule and settle their fee. The history stays on the book.
Page tracking
The physical book has pages. So does this one. Staff record the page a member's entries sit on.
Dormancy handled
Books that go quiet are tracked against Ghana's dormant-account rules, and interest stops while they are dormant.
Withdrawals
Requested, approved, then paid.
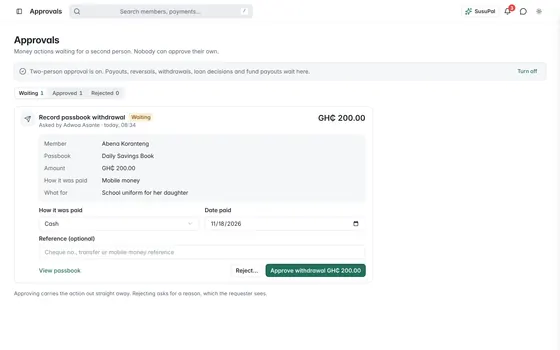
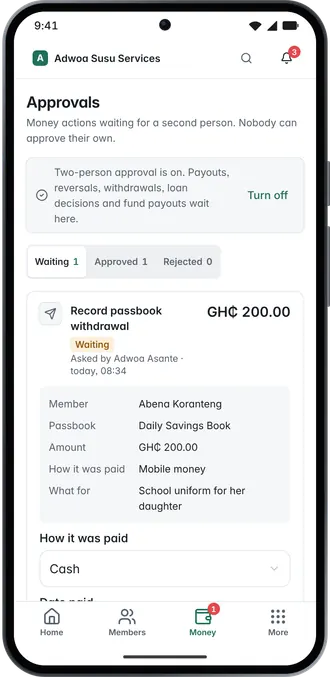
A member or agent requests a withdrawal. A staff member with the right role approves or declines it. Only then is a payout recorded, with its channel and reference. If you have turned on dual control, a second approver is required before the money moves.
Approval flow
Every withdrawal carries who asked, who approved and when.
Two-person approval
Turn it on and a second person must approve each withdrawal before it is paid.
How two-person approval works ›Savings-secured lending
A passbook balance can secure a loan. The lien is recorded on the book.
See lending ›
The member's copy
A copy the member holds, that ties to yours.
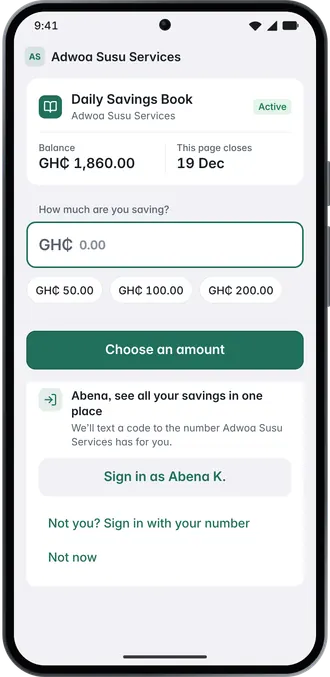
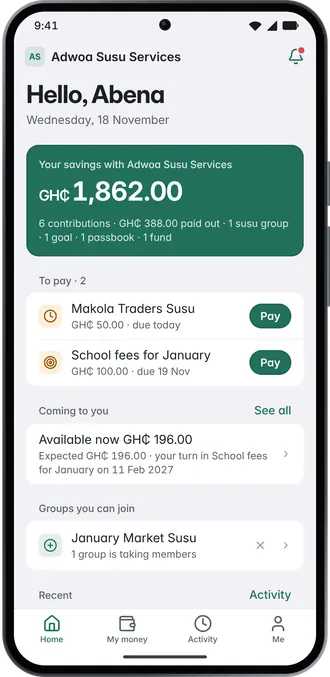
Members see their passbook in the portal, with every deposit, fee, interest line and withdrawal, and a balance that matches yours to the pesewa. Both sides read the same book, so the argument about what was paid when ends.
Pay by MoMo
Deposit into a passbook from the member's phone on any of the three networks.
Statements
Download a statement for any period.
Cycle reminders
A reminder before a cycle closes, in the channel the member uses.
Everything in the box
The paper book, without the paper risks.
- 01Cycles and fee modes
- The structures collectors already use.
- 02Page tracking
- Pages fill up like the book.
- 03Withdrawal approvals
- A second person approves.
- 04Cycle reminders
- Automated, keeps members on schedule.
- 05Savings-secured lending
- A balance secures the loan.
- 06A copy the member holds
- Always current, always checkable.
Works with
Member portal
Members pay by mobile money, check their Ghana Card, apply for a loan, ask to withdraw and download statements, all from their own phone.
Lending
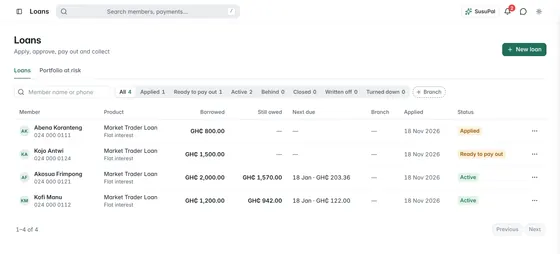
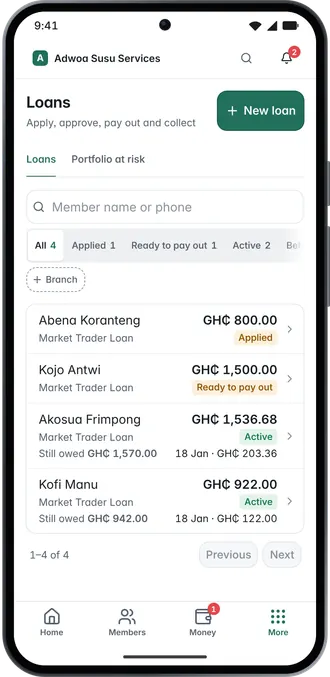
Application, approval, paying out, repayments, then settlement or write-off. Every step is recorded with who did it.
Accounting
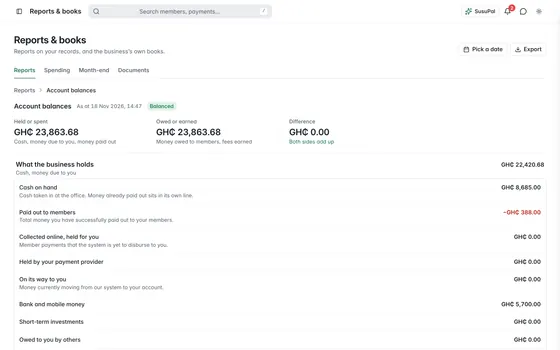
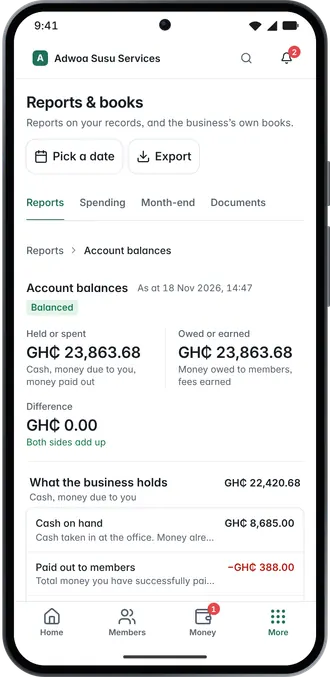
Books that always balance, on every plan. Each payment is recorded on both sides of the books, so your trial balance ties out and any accountant can check it.
Loyalty
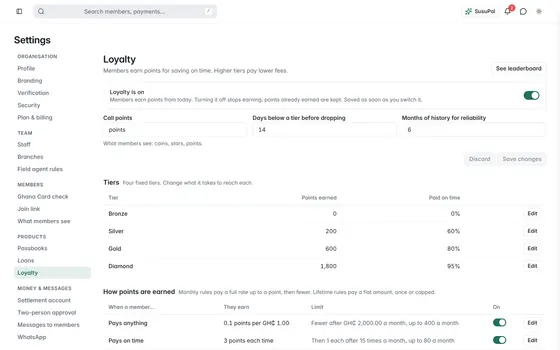
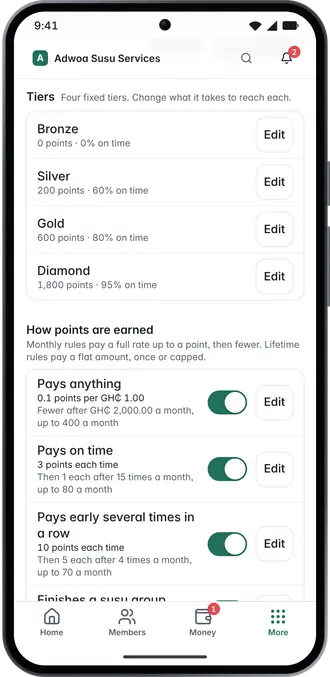
Bronze to Diamond tiers earned on paying on time. Points rules you control, with a leaderboard members can see.
FAQ
Questions people ask about passbooks
Can I run passbooks without fees or interest?
Yes. Both are optional rules on the product. A passbook can be a plain running balance.
How is interest added?
It is worked out every day and added once a month, as its own line, separate from deposits. Only organisations licensed to take deposits, such as microfinance banks and credit unions, can pay interest on savings.
What if a member loses their paper book?
The record is in SusuPaa. Their portal shows the same balance and history. The paper is just a convenience.