For microfinance institutions
Your loan book, your susu book and your ledger, all in one system.
Portfolio at risk updates as you post, and provisioning is one run away. Board reporting comes out of the same books.
What is going wrong today
Six ways the numbers get away from you.
Agent cash doesn’t tie out
A collector banks GH₵ 4,200, the book says GH₵ 4,650, and nobody can say where the gap opened or when it started.
PAR is seen too late
A loan sits overdue for weeks because nothing flags it until someone opens the file.
Provisioning lives in a spreadsheet
Ageing buckets and rates are maintained by hand, outside the system, and reconciled back in afterwards.
Nothing stops a single member of staff
One person can record a payout, reverse a deposit and forfeit a balance with nobody else in the loop.
Board reporting is assembled by hand
From sources never designed to agree with each other.
Every figure needs a defence
An accountant who cannot trace a number will not accept it.
More staff will not fix this. It’s a controls problem. See how two-person approval and an audit log close it.
Why SusuPaa
One system for risk, control and reporting. PAR, provisioning and two-person approval all run inside the platform.
Risk is live
Arrears are flagged as instalments fall due. Portfolio at risk is reported by ageing bucket on demand.
Controls that hold
Disbursement, write-off and withdrawal can each require a second approver. No single action clears itself.
Ready for your return
Accounts map to the GCSCA monthly return. Month-end works out the return's figures from your books and exports them.
The Custom plan
What the Custom plan runs on.
- 01PAR by ageing bucket, on demand
- The headline health number of your loan book, updated the moment a loan moves.
- 02Provisioning that posts to the ledger
- Configurable ageing bands and rates, with provisioning runs you can trace.
- 03Agent cash reconciliation
- End-of-day submission, variance routed to a supervisor, commission statements alongside.
- 04Two-person approval
- Withdrawals, loans and write-offs can require a second person. You see who approved it, for how much, and when.
- 05SusuPal understands your numbers
- Ask what’s overdue, or what a ratio was last month. The answer comes straight from your own portfolio.
- 06Your brand, your branches
- White-label with your own domain, unlimited branches, Ghana Card verification at collection time.
Products
What this audience runs on.
Lending
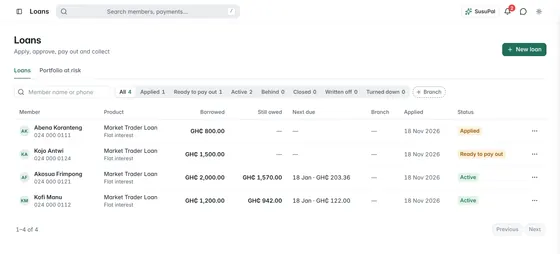
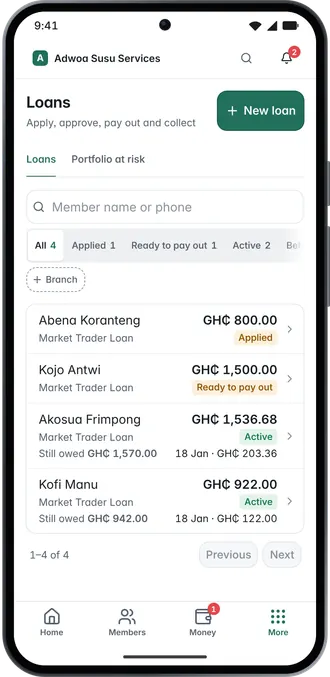
Application, approval, paying out, repayments, then settlement or write-off. Every step is recorded with who did it.
Accounting
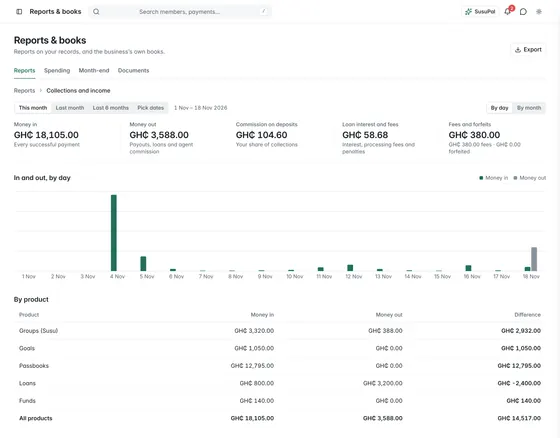
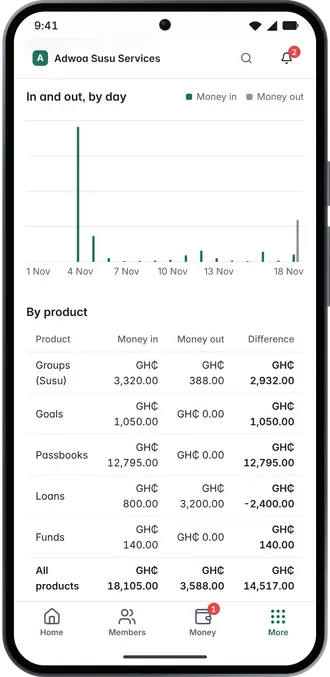
Books that always balance, on every plan. Each payment is recorded on both sides of the books, so your trial balance ties out and any accountant can check it.
Passbooks
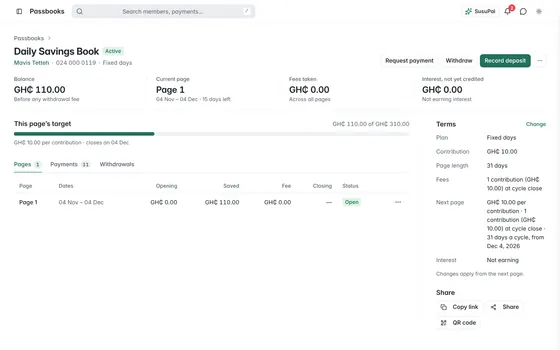
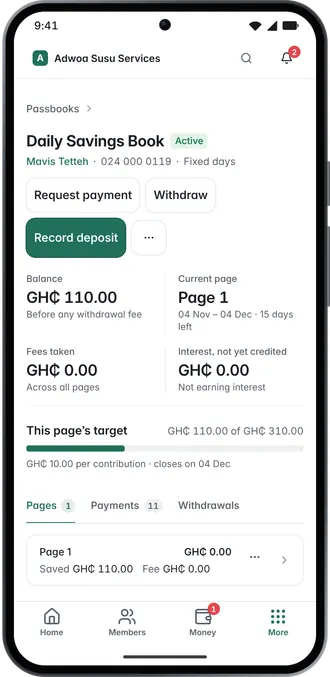
Pages, fees and a running balance, with an approval on every withdrawal. It is other people’s money.
SusuPal
A read-only AI assistant for your SusuPaa account. Every answer comes from your own books, members, loans and reports. Never from memory, never invented.